
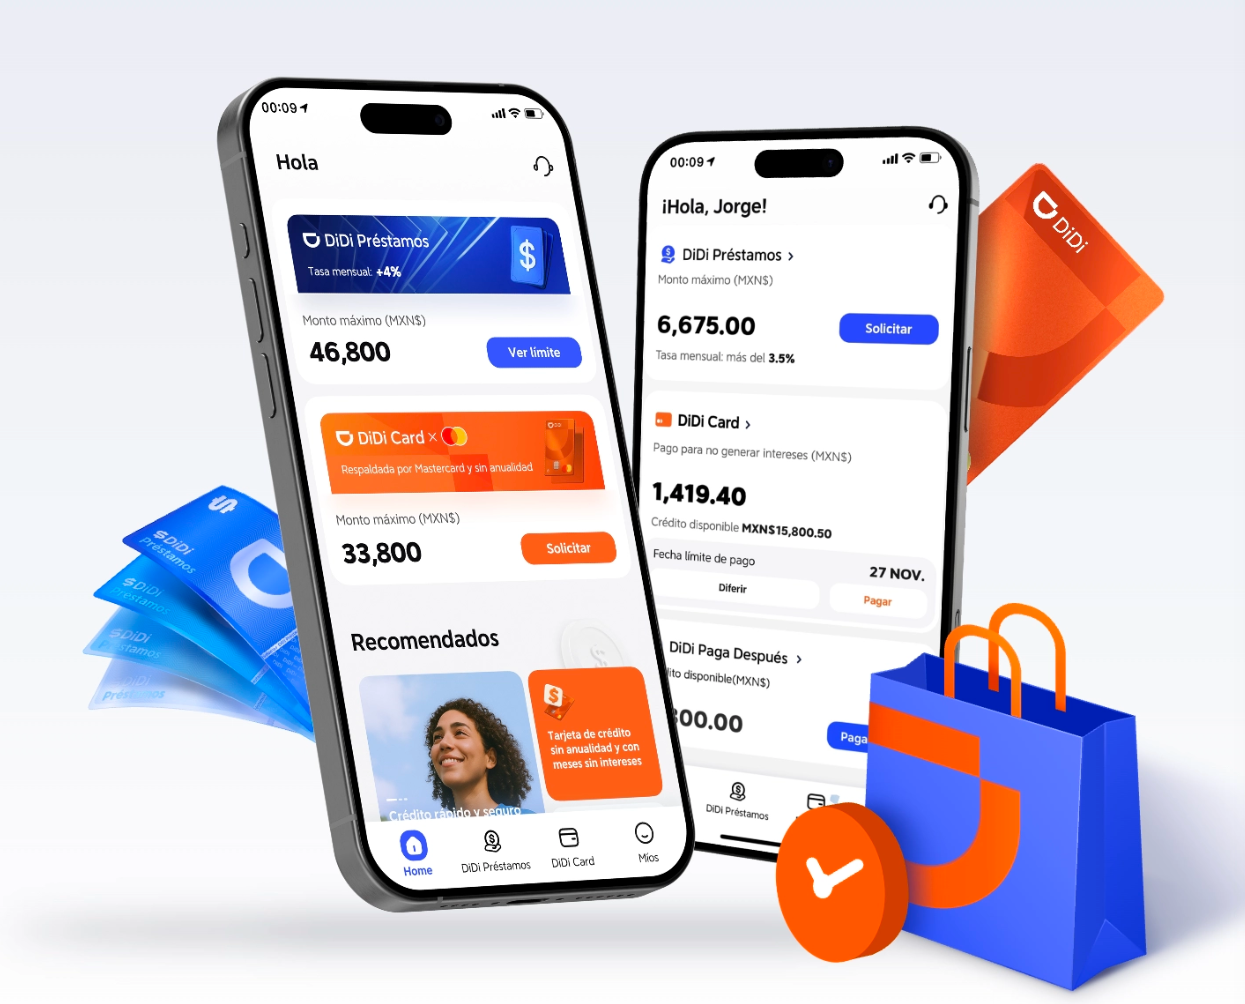
A user-first look at why speed matters
Aye, folk want cash when the need’s pressing — not next week. This piece is built for the person who needs clear, usable answers about instant loan processing and how it affects your wallet. Here I’ll walk you through the practical bits of APR, underwriting timelines, and disbursement speed, and how didi finanzas fits into that picture. The tone’s plain, the aim’s helpful, and every note leans toward what a user actually experiences at the moment their phone lights up with a loan offer.
How processing speed translates into real benefit
Quick processing isn’t just convenience. Faster underwriting and disbursement reduce the risk of short-term borrowing costs rising or late fees stacking up. If an urgent repair or medical bill lands, an instant loan paid out within hours can mean the difference between a small hiccup and a long, costly chain of follow-up charges. That’s the measure most of us care about: time saved and costs avoided. Keep an eye on the stated APR and any upfront fees; they tell you what the speed truly costs.
What DiDi Finanzas does differently for drivers and everyday users
The practical advantage lies in workflow. DiDi’s approach aligns driver earnings data with underwriting logic — a quicker credit decision when recent trip revenue is verifiable. That reduces friction in the application. But speed’s no use without clear repayment terms. Look for transparent repayment schedules, and whether lending is tied to your credit score or driver performance. For those weighing trust, some readers look up whether didi finanzas es confiable — and rightly so; trust is as vital as velocity in finance.
Common mistakes people make when choosing an express loan
Folk rush for the fastest offer and forget to check effective cost. Mistakes to avoid: ignoring total repayment, overlooking processing fees, and not confirming the exact disbursement window. Also, don’t assume every “instant loan” gives instant funding — the stated decision time and actual bank transfer time can differ. A short pause here could spare you a longer trouble later — trust the numbers, not only the marketing.
Alternatives and sensible comparisons
If speed’s less critical, a short-term credit card advance or a small personal loan from a local credit union often carries lower APRs and clearer terms. Peer-to-peer lenders can be faster than banks but check reputation. Compare offers by three metrics: total cost (including fees), net time to receive funds, and clarity of repayment terms. These give you a fair yardstick across instant loan products, fintech options, and more traditional lending channels.
Real-world anchor and a grounded approach
Grounded in a practical-explanatory stance, this guide draws on what drivers in Mexico City have reported — quick access to funds after a long shift can steady a week of earnings. World Bank commentary on Latin American fintech growth supports that faster, data-driven credit is reshaping access — but local trust and clear terms remain decisive. Keep the local landscape in view when assessing any express lending product; regional payout systems and bank clearing cycles change how “instant” looks on the ground.
Three golden rules for choosing fast funding
1) Prioritise clear total cost: add APR and all fees to see the full sum you’ll repay. 2) Confirm actual disbursement time: a loan decision in minutes still needs a bank transfer window. 3) Check reliability and support: verify whether the provider has local customer service and transparent underwriting policies. These three make for a sturdy selection framework when speed matters.
Final thought — speed without clarity is a poor bargain; speed with transparent terms is a helpful tool. — DiDi Finanzas