
Why speed matters for drivers and couriers
For people who rely on daily earnings, the time between a completed trip and money in the bank is everything. Riders, drivers, and delivery partners in Mexico City and beyond need predictable cash flow to cover gas, food, and bills. didi finanzas promises faster access to earnings by handling disbursement and settlement with an eye toward real-world needs. Faster transfers reduce downtime and stress; that practical benefit is what makes processing speed a user concern, not just a technical metric.
How SPEI, settlement, and the app work together
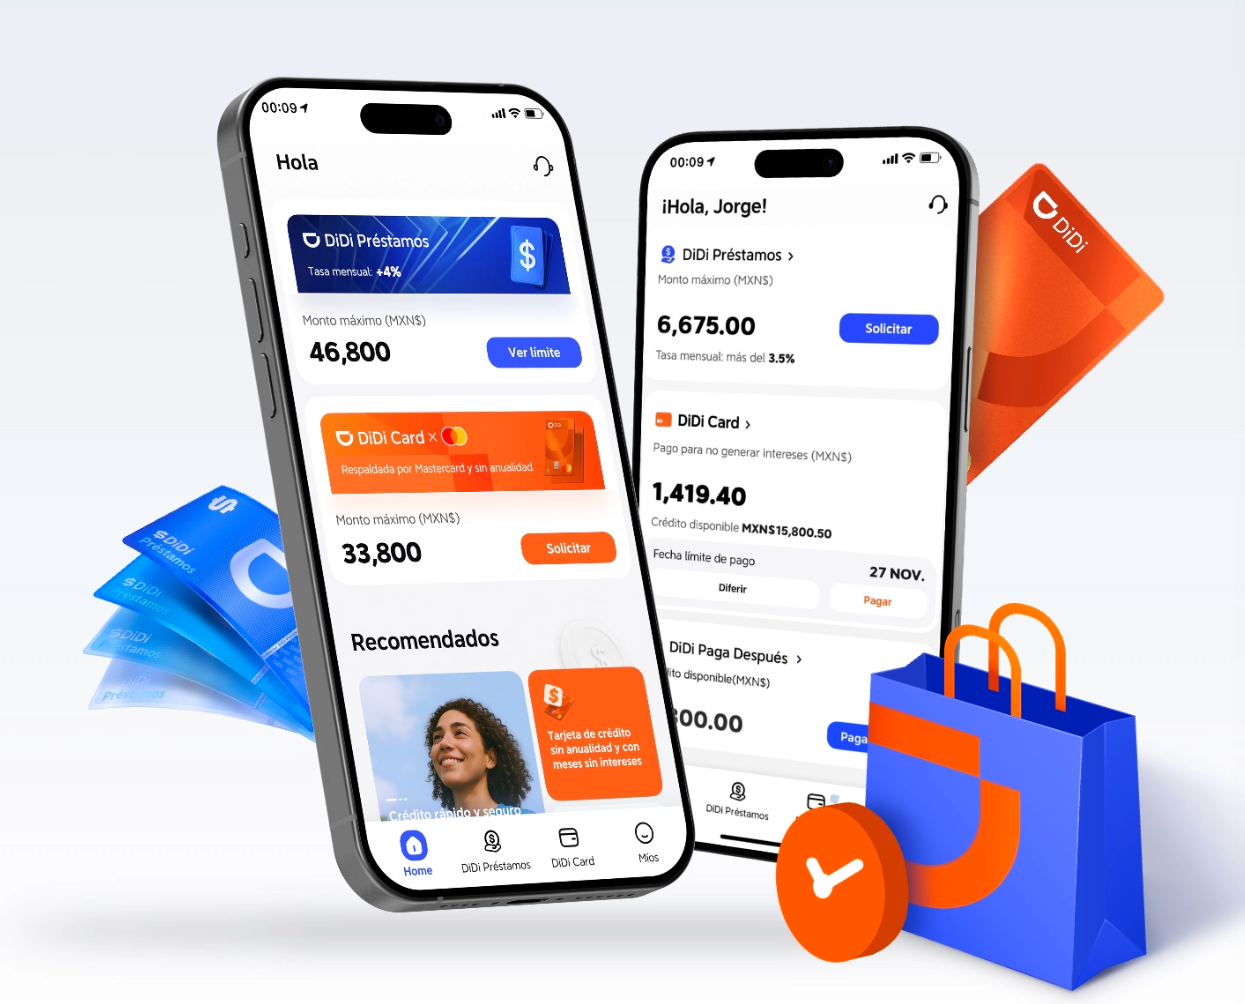
SPEI (Sistema de Pagos Electrónicos Interbancarios) is Mexico’s backbone for electronic transfers and enables near-real-time movement between banks. On top of that rail, platforms must manage KYC, internal ledger updates, and API calls to push funds out. The didi finanzas app coordinates those steps: it verifies identity, queues payouts, and initiates SPEI disbursements. Transaction latency depends on each stage — verification, bank cutoffs, and network acknowledgements — so the app’s orchestration matters just as much as the SPEI rails.
Where delays typically originate — and common mistakes
Most hold-ups are avoidable. Common user-side issues include incomplete KYC, mismatch in account names, or using a bank that applies longer internal holds. On the platform side, delays can come from batch processing at certain times of day or manual reviews for unusual activity. Pay attention to these pitfalls — they’re routine yet fixable. — Also note that some banks in smaller Mexican states may have different processing windows than those in Mexico City, which affects final credit time.
Practical steps to get funds faster
Small changes yield steady gains. Follow these steps to reduce latency and improve predictability:
– Complete and periodically re-check your KYC details in the app so identity checks don’t trigger manual review.
– Use a primary bank account known for fast SPEI credits (major national banks tend to be quicker).
– Time withdrawals to avoid nightly batch cutoffs; initiating transfers earlier in the day often helps.
– Keep the didi finanzas app updated to benefit from improvements in API integration and UX that speed processing.
Alternatives and how they compare
If immediate liquidity is critical, some drivers use instant-cash advances or third-party wallets as a bridge. These can be helpful but typically involve fees or short-term interest. Direct SPEI payouts remain the most cost-effective path when the app and user settings are aligned. Compare net receipt time and fees rather than headline speed — a quick advance with high fees can cost more in the long run.
Real-world anchor and what it shows
Observation from drivers around Mexico City shows that improvements in app-side verification and clearer payout windows have cut average cash-access waiting times in recent years. That local evidence aligns with how payment systems operate globally: tighter identity processes and better API orchestration reduce failed transfers and rework, which in turn reduces total settlement time.
Summary and advisory — three golden rules
To evaluate payout speed and choose the right approach, use these three metrics:
1) Net receipt time: measure minutes or hours from payout initiation to bank credit under normal conditions. This tells you the real-life wait.
2) Failure rate: track how often transfers require manual intervention or bounce. Low failure means smoother cash flow.
3) Total cost: include fees for instant advances, potential FX or bank fees, and opportunity cost of delayed funds. Lower overall cost beats a flashy speed claim.
Apply these rules when you compare the didi finanzas app to other options — they clarify trade-offs and reveal where improvements matter most.
Parting thought
Fast, reliable payouts are both a technical challenge and a human need; when systems respect that, drivers spend less time waiting and more time working. DiDi Finanzas sits at that intersection as a practical solution for quicker access to earnings — it’s about steady, usable money in your pocket. –